
Nyumba Smart: Tanzanian financial institutions benchmark KWFT’s housing finance model
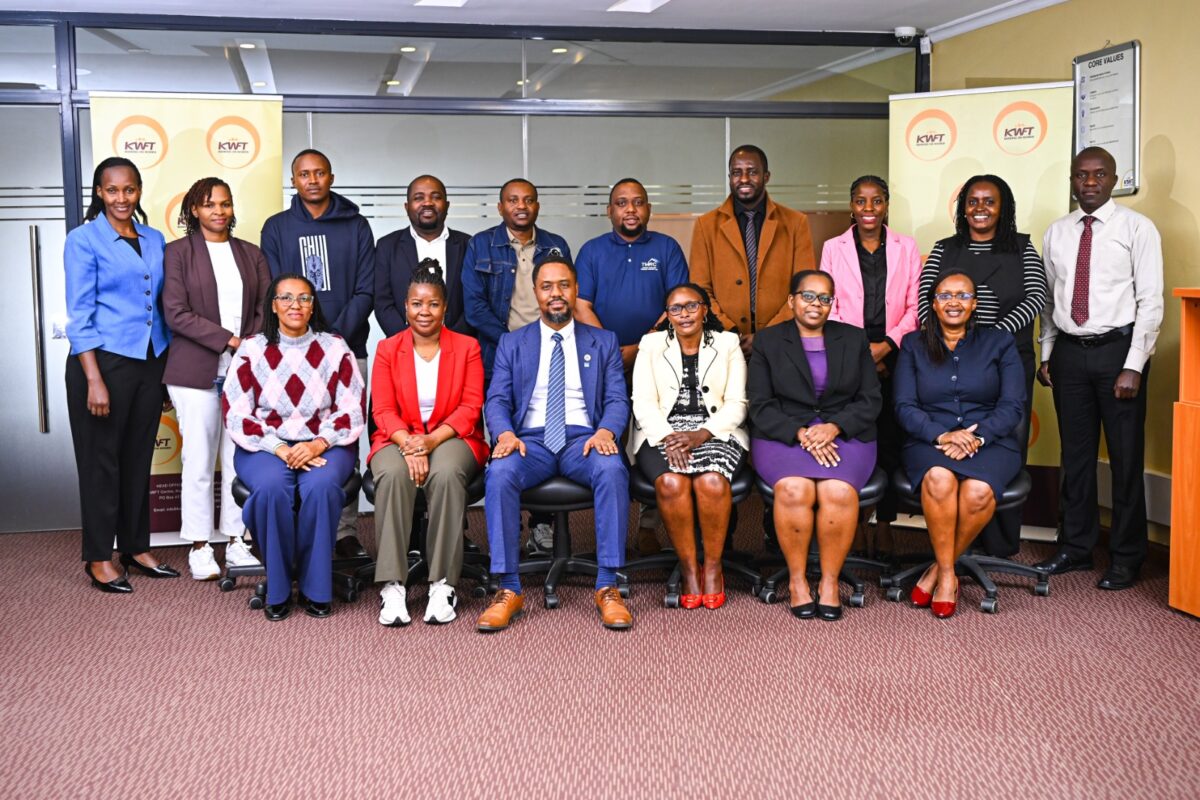
Tanzanian financial institutions visited KWFT to study our Nyumba Smart housing finance model and how affordable financing can help low-income households build and improve their homes in stages which provided the institutions with an opportunity to examine a housing finance model designed around the way many low-income households actually build their homes – one stage at a time.
The delegation, led by Hellen Waigwa, Manager, Housing Finance Systems at Habitat for Humanity International (HFHI), included representatives from Tanzania Mortgage Refinance Company (TMRC), Tanzania Institute of Bankers (TIOB), NMB Bank Tanzania and CRDB Bank PLC.
The group visited KWFT before travelling to Machakos County to see firsthand how Nyumba Smart is helping families improve their homes, including visiting customers who have used the financing to fund different stages of construction.
Financing a home in stages
Nyumba Smart was developed for customers who may not have the income, collateral or financial capacity to take on conventional mortgage finance.
Instead of requiring a household to finance an entire house through one large loan, the model allows customers to borrow for specific improvements as their needs and finances allow.
This can include putting up walls, replacing a roof, adding a room, improving floors or completing other construction work. Financing can cover different stages, from foundations and walls to roofing and finishing.
The approach is consistent with findings from a study on systemic barriers to housing finance in Kenya, which found that many households build gradually using savings or microloans. The study put the average construction period at 3.3 years and identified high building costs, documentation requirements, limited collateral and irregular incomes as some of the barriers to conventional housing finance.
Nyumba Smart therefore starts with the customer’s housing need.
KWFT assesses the proposed work, its estimated cost and the customer’s ability to repay, taking into account cash flow, savings and existing financial commitments.
The model also uses approaches suited to customers with informal incomes, including cash-flow-based lending, community-based distribution, social guarantees and other forms of collateral. It also has a strong focus on women-led households.
The result is financing that follows the customer’s housing journey rather than requiring the entire project to be completed at once.
Beyond construction
The Nyumba Smart portfolio has also broadened the scope of what can support better housing conditions.
Financing can cover areas such as water, sanitation and hygiene, lighting, cooking facilities and clean energy, alongside construction, renovation and incremental building.
This recognises that improving a family’s home is not limited to putting up a new structure. Access to safer sanitation, better cooking facilities, reliable lighting and cleaner energy can also improve living conditions.
A model built around affordability
The sustainability of housing microfinance depends on more than the number of loans issued. Customers need financing they can manage, while lenders need to maintain a healthy and sustainable portfolio.
KWFT’s experience has centred on balancing these needs through appropriate loan sizes, flexible repayment arrangements and assessment of repayment capacity based on cash flow.
This is supported by customer eligibility processes, risk management, pricing and systems that enable the loans to be delivered efficiently.
By December 2024, Nyumba Smart had issued more than 100,000 housing loans, serving more than 83,000 customers. The portfolio has a performance rate of 98 per cent.
The scale of the programme provides a practical example of how housing finance can be structured for households that are not well served by conventional mortgages.
Lessons for financial institutions
For the Tanzanian institutions, the benchmarking visit offered an opportunity to look beyond the loan product and examine the systems that support its delivery.
These include understanding customer needs, breaking construction into manageable stages, training field staff, using technology and working with partners across the housing sector.
The latest visit builds on a first benchmarking visit by Tanzanian financial institutions to KWFT in 2024, reflecting growing regional interest in approaches that can extend housing finance to households underserved by conventional mortgage lending.